 Executive point of view
Strategy and economics · From AI-enabled to AI-native
The rebuild
dividend.
The investment case for the AI-native enterprise.
Why adding AI tools to existing work returns a cost-sized benefit, why rebuilding the work returns a P&L-sized one, and what enterprise capability makes the second affordable at scale.
Executive summary
AI is being bought as a cost. The returns are cost-sized.
Most AI budgets buy tools added to existing work. Spend scales with headcount, and the benefit is minutes saved per person.
Intelligence Debt: a widening gap between the AI the enterprise could run and the AI it does.
Rebuild the workflows that matter to the P&L, on a capability that is built once and reused.
Fund it as an investment, staged against results and owned by the leadership team.
Nearly every large enterprise uses AI, and very few can find it in the P&L. Everyone has the same models. The difference is how the money is spent.
Most AI budgets buy tools: assistants, copilots, and AI features inside software already in use. The work stays the same, done a little faster. This is the AI-enabled enterprise. Bought one tool at a time, it also builds Intelligence Debt.
A smaller group picks a workflow that matters to the P&L and rebuilds it, so that AI does the work and people handle exceptions, judgment, and approval. This is the AI-native enterprise, and it is the group reporting EBIT impact.
Rebuilding is an investment. Money goes in before returns come out, and the return depends on what is built once and reused. That reusable part is an enterprise AI capability. It decides whether the tenth workflow costs a fraction of the first or the same again.
McKinsey, The State of AI in 2025.
Sections 01 to 03 make the economic case, 04 and 05 show what rebuilding takes, and 06 to 08 cover funding, the cost of waiting, and what to watch.
01 · The paradox
Adoption is nearly universal. Returns are rare.
Three independent studies describe the same gap from different angles.
The usual explanations do not hold. The 6% buy from the same model providers as everyone else. Price is not the constraint either: per-token prices fell 280× in two years (Stanford HAI AI Index), yet about seven in ten enterprises overran their AI budgets (DoiT; FinOps Foundation; WitnessAI).
What the money bought
In most enterprises AI arrived like a software upgrade: licenses per seat, features inside existing applications, pilots on existing processes. Each purchase was reasonable, and each left the work untouched: the same queue, the same handoffs, the same number of people on each case.
The benefit is real, and it is bounded. An assistant that saves an analyst half an hour a day has saved half an hour. Unless the process changes, that time is absorbed into the day and no cost line moves. The result is a large license bill and a productivity gain nobody can audit.
They changed the work. McKinsey finds AI high performers nearly three times as likely as other organizations to have fundamentally redesigned their workflows when deploying AI.
The technology is the same on both sides of the gap. What differs is whether the process around it was rebuilt.
02 · A precedent
Electricity took a generation to pay.
The last general-purpose technology to reach industry opened the same gap between having it and profiting from it. The gap closed for a reason leaders can act on.
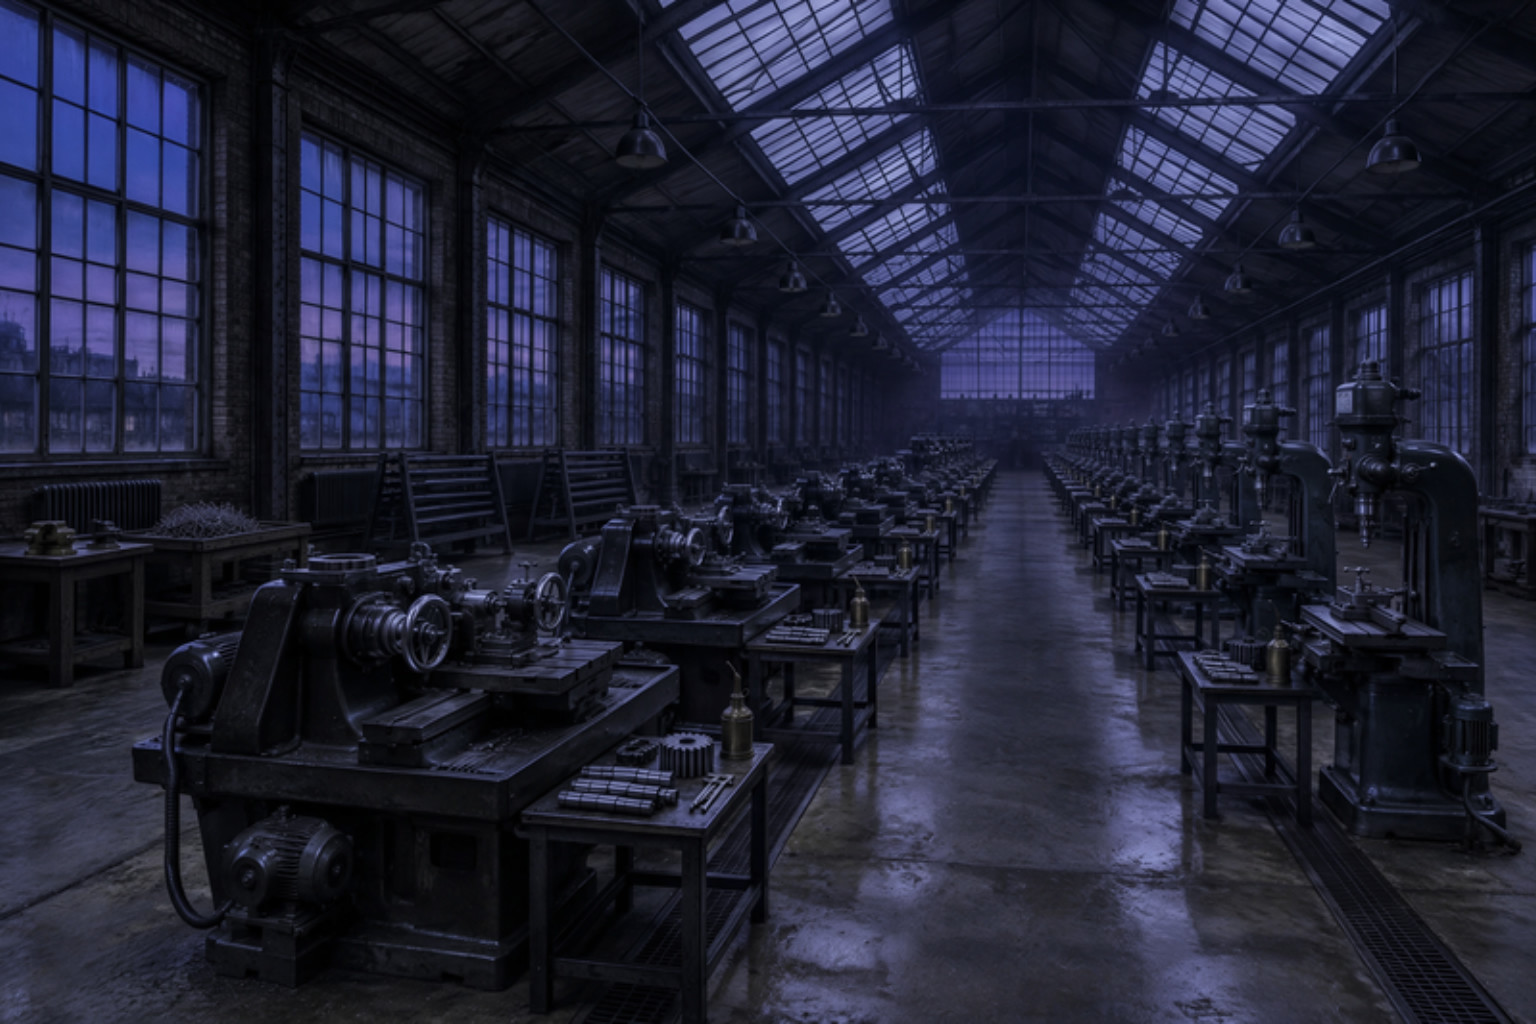
In 1899, electric motors supplied under 5% of the mechanical drive in American factories. Owners who adopted them did the sensible, incremental thing: they swapped the steam engine for one large electric motor. Power still ran through overhead shafts, and machines stood where the shaft reached. The saving was a cheaper way to turn the same shaft.
The gains came when a later generation gave each machine its own motor. Machines could then stand in the order the work flowed, and buildings went single-story. By 1929, electric motors provided about 78% of factory drive capacity, and manufacturing productivity accelerated sharply through the 1920s.
Economist Paul David traced the delay to this: the return came from the redesigned factory. The motor only made the redesign possible.
Applications moved to the cloud unchanged produced a new bill. Applications rebuilt for it produced the agility. With AI, most enterprises have so far fitted the electric motor to the old shaft.
03 · Two ledgers
The same technology, on two different ledgers.
AI-enabled and AI-native are usually described as stages of maturity. They are more useful read as two kinds of spending.
Why the two ledgers behave differently
A cost is managed by spending less of it. Book AI as an operating cost and every incentive points to fewer seats, cheaper tokens, and narrower pilots. An investment is managed by what it earns, which points to the workflow, its baseline, and its due date.
An AI-native enterprise still buys assistants. The mistake is expecting the first ledger to deliver the second ledger's result.
The difference between what a workflow costs to run once it is rebuilt around AI and what it cost when AI was added to it. It is paid every year the workflow runs, it grows as the workflow improves with use, and no competitor can buy it.
04 · One workflow, rebuilt
What rebuilding a workflow changes.
Back-office document processing in financial services is a fair test: high volume, regulated, and already a target for AI tools.
- Staff read, key, and check each document, with an assistant to summarize and draft
- Every case passes through the same queue and the same approvals
- Every request goes to a frontier model at frontier prices
- Controls are applied by review, after the fact
- Cost follows volume and headcount
- A domain-tuned small model processes standard documents end to end
- Hard cases route to a larger model, and ambiguous ones to a person
- Guardrails and an audit trail apply to every request by default
- Staff handle exceptions, judgment, and approval
- Cost per document falls as volume rises
A financial services group's back-office workloads
Rebuilt on Bud Novaria AI OS on the group's own infrastructure: a domain-tuned small language model for standard documents, with a larger model in reserve for complex cases.
Annual total cost of ownership. Bars drawn to scale.
Moved to a small model the institution owns.
Moved to the cases that need them.
Built into the path every document takes.
The saving came from those three decisions, and only a rebuilt workflow allows them. A better assistant would have delivered none. They need authority over the process, which makes rebuilding a leadership decision before a technology one.
05 · The capability
One rebuilt workflow is a project. Fifty need a factory.
A determined team can deliver the first rebuilt workflow with whatever tools are at hand. By the fifth, nothing built for one team can be used by another.
The five parts every AI workflow runs on
Whoever builds it, every AI workflow is made of the same five parts. Together they are an AI factory: data and questions go in, finished work comes out.
Where the factory lives today
AI reaches most enterprises by four routes at once. None leaves the enterprise holding all five parts. The matrix below shows which parts each route puts on the enterprise's books.
| Route, and what it delivers | Apps and agents | Governance | Inference | Models | Infrastructure | Owned |
|---|---|---|---|---|---|---|
| Employees building on frontier AI toolsSpeed. The fastest route and the least governed | 1 of 5 | |||||
| AI features inside software already licensedConvenience. It arrives on the software bill | 0 of 5 | |||||
| A platform built by internal ITControl. The route business units cannot wait for | 4 of 5 | |||||
| A consultant or managed serviceAn outcome, delivered finished and run by someone else | 0 of 5 | |||||
| An enterprise AI capabilityOne platform and one team, reused by every workflow | 5 of 5 |
Ownership decides the return. The dividend compounds only when the next workflow reuses the same governance, data connections, models, and team. So the enterprise capability is a short list held in common: one platform, one operating team, one catalog of reusable patterns, and one set of numbers the CFO trusts.
To make the tenth workflow cheaper, faster, and safer to deliver than the first.
06 · The investment
Expect a J-curve, and stage the spending.
Investments in a general-purpose technology share a profile: the spending comes first, and the return arrives later and is larger.
Economists Brynjolfsson, Rock, and Syverson named it the productivity J-curve. Redesign, data, and skills cost money before they register as output. Leadership teams that expect the dip fund through it. Those that do not tend to cancel at the bottom.
What the first tranche funds
Three to five value streams, chosen for P&L weight, sequenced by payback, each with a named business owner.
A small platform team for the shared parts: identity, data access, guardrails, model evaluation, observability, and cost tracking.
One accountable executive over both. Split ownership is the surest route to an estate of pilots.
The first rebuilt workflow carries the cost of the platform, the team, and the patterns, so on its own it can look worse than buying a tool. Judge the program on what the third and the tenth cost to deliver.
06 · The investment, continued
Ownership can be reached in stages, without capital up front.
Owning the capability does not mean buying it on day one. Bud's route on Bud Novaria AI OS starts with one outcome, paid for on delivery, and moves ownership across as results arrive.
The money is staged. The architecture is not. Every stage runs on the same platform, so nothing is rebuilt. That separates it from buying one tool at a time.
The gates · Evidence that releases the next tranche
Each tranche is released on evidence from the one before. A staged rebuild that disappoints is stopped at the first gate, at the cost of one workflow's budget.
07 · The cost of waiting
Incremental spending has a cost of its own.
Staying on the first ledger feels prudent because each purchase is small. Three things grow while the enterprise waits.
Prices fell 280× and budgets overran anyway, because agents multiply calls and volume outruns price. AI cost is set by architecture, and architecture is not on the first ledger, so nobody manages it.
Every tool bought and every model chosen on its own widens a gap nobody sees in aggregate. Exposure grows with it: EU AI Act penalties run up to 7% of global turnover.
A competitor that started rebuilding delivers each workflow for less than the last. That lead widens every quarter and cannot be bought back with licenses.
The gap between the AI the enterprise could run and the AI it does, plus the cost of closing it.
A staged rebuild that disappoints costs one workflow's budget. A delay that turns out to be wrong costs every year of dividend the enterprise did not collect.
08 · The leadership agenda
Five numbers to watch. Five questions to ask.
Five numbers show whether the spending is behaving like an investment. Each needs an owner, a baseline, and a monthly review.
Five questions for the leadership team
The technology is the same for everyone. The return goes to the enterprises that rebuild the work and own the capability to keep rebuilding it.
Get started with Bud
Put your data on it.
Pick one workflow that matters to the P&L. In a 30-day proof of concept on your infrastructure, Bud rebuilds it on Bud Novaria AI OS and measures it against a metric you choose.
contact@bud.studio · budecosystem.com/poc
Transforming to an AI-Native Enterprise, the practitioner's playbook · The Case for Enterprise AI Management · The Enterprise Buyer's Guide to Foundational AI Platforms, all at budecosystem.com/whitepapers. Intelligence Debt, the featured article, at budecosystem.com/features/intelligence-debt.
Bud Novaria AI OS is the AI operating system for the enterprise: one native stack from silicon to agents, on any silicon, in any cloud, on-premises, or air-gapped, under one governance model.
Sources and method
Every figure names its source where it appears. Figures 2, 3, 5 and 6 are schematics.
© 2026 Bud Ecosystem Inc. All rights reserved. Bud, Bud Novaria, Bud Gaia and the Bud mark are trademarks of Bud Ecosystem Inc. Other names are the property of their owners; no endorsement is implied. Capabilities are described as designed; results depend on models, data and workload.
12